The Price Tag Is Public: Testing a Cost-Plus Pharmacy Against Your 2026 Copay
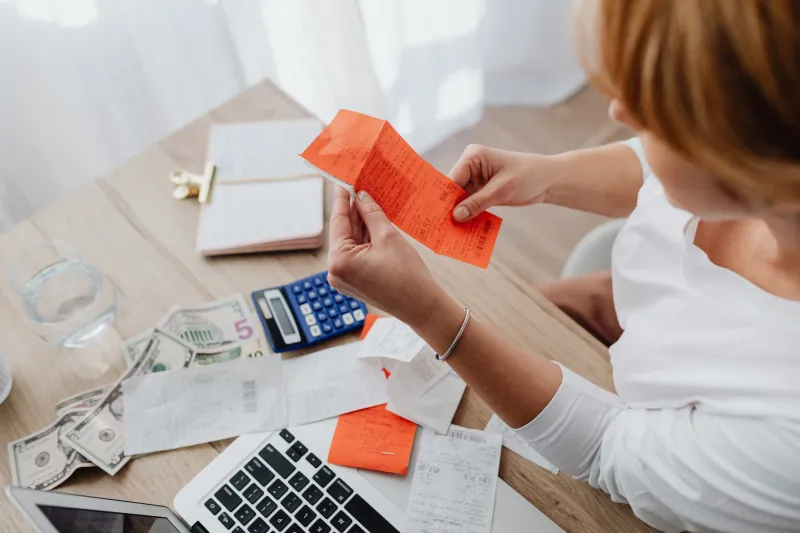
Cost-plus pharmacies have a certain appeal for anyone who has ever stared at a pharmacy receipt and wondered what all those numbers mean. Instead of a mysterious final price, these online outfits publish a formula: the drug’s cost, a set markup, and shipping. That transparency is refreshing. It is also not a magic coupon. In 2026, a cost-plus quote can beat your copay for some prescriptions — and lose badly for others.
The smart move is not to move every bottle online. It is to treat cost-plus pricing like one more quote in your pharmacy shopping file, right next to your insurance copay and your discount card price.
What Cost-Plus Really Means
A cost-plus pharmacy generally buys medications and sells them at the published acquisition cost plus a fixed markup, then adds shipping. You pay cash. Your insurance plan is usually not involved. Some services also offer discount-card pricing or partner networks, but the core pitch is simple: here is the medicine cost, here is our fee, here is the total.
That is different from the price you see at a traditional pharmacy counter. Your copay is a share of what your plan has negotiated, not necessarily the pharmacy’s cash price. A $30 copay can sound high until you learn the plan’s allowed amount is $180. A $12 cost-plus quote can sound low until you add $5 shipping and realize you need a 90-day supply.
Where the Math Gets Interesting
Cost-plus pricing often looks best on certain generic maintenance drugs — the kind you take every day for blood pressure, cholesterol, thyroid function, or allergies. Those drugs may carry generous retail markups at a local pharmacy, and a cash quote can undercut both the copay and a discount card.
It looks less impressive when your plan charges a low tier copay, when you have not met a deductible, or when the drug is brand-name only. Brand drugs often have manufacturer copay cards or patient assistance programs that beat a cash quote. Specialty drugs, refrigerated drugs, and anything requiring special handling are usually a different conversation entirely.
Here is the comparison that matters: total cost for the same drug, same strength, same quantity, and same days supply. Not the sticker price. Not the per-pill price alone. The full bill, including shipping, for the fill you will actually use.
The Kitchen-Table Comparison
Start with the prescription label or your pharmacy app. Write down the exact drug name, strength, quantity, and days supply. Then collect quotes.
Ask your current pharmacy for both the insurance price and the cash price. They are not always the same, and the cash price may be lower than your copay. Check a discount card for the same details. Then get a cost-plus quote that includes shipping and any membership fee. If the service offers auto-refill, ask whether shipping is charged per bottle or per order.
A simple worksheet helps:
- Local pharmacy with insurance: copay plus any deductible remaining
- Local pharmacy cash price: total at the counter
- Discount card price: total at the counter
- Cost-plus pharmacy: drug cost plus markup plus shipping
- Cost-plus 90-day order: total divided by 90 for a per-day cost
The per-day number is the great equalizer. A 30-day fill that saves $8 may not be worth the shipping wait. A 90-day fill that saves $45 might be. But only if you have room to store it, the expiration date works, and you are not changing doses next month.
The Fine Print That Can Eat the Savings
One overlooked issue is plan credit. If you pay cash outside your insurance, that purchase usually will not count toward your deductible or out-of-pocket maximum. For people with high drug spending, that can matter more than a few dollars saved on one bottle. Ask your plan before you assume a cash purchase helps you reach the next coverage stage.
Also check whether the cost-plus pharmacy can bill insurance at all. Many cannot, or they choose not to. That is fine for a cash experiment, but it means you are managing two workflows: one for the drug you buy online and one for everything else.
Keep receipts. If you use a health savings account or flexible spending account, confirm the purchase is eligible and that the receipt shows the required details. Do not assume every online pharmacy receipt will satisfy your account administrator.
Which Prescriptions Are Poor Fits
Cost-plus is a bad fit for anything you need today. Antibiotics, pain relievers after a procedure, and other short-term prescriptions belong at a local pharmacy where you can pick them up in an hour. The same goes for controlled substances, which often cannot be shipped or transferred easily.
Be cautious with refrigerated drugs, compounded products, and medications that need special packaging. Shipping delays happen. Weather happens. A box that sits on a hot delivery truck is not a bargain.
Brand-name drugs, specialty medications, and anything with a manufacturer copay card deserve a separate check. A cost-plus quote may be higher than the manufacturer’s program or your plan’s specialty pharmacy price. And if you need a pharmacist to walk you through a new inhaler or injectable, a local counter has real value that does not show up in the quote.
Shipping, Refill Timing, and the Last-Pill Problem
Maintenance medications can work well through a cost-plus pharmacy if you plan around the delivery window. Order when you have at least a week or two of pills left. Ask how long shipping usually takes, whether a signature is required, and what happens if the package is delayed or damaged.
Set a refill reminder before you place the first order. Auto-refill can be convenient, but confirm you can pause it when your dose changes or you switch plans. Keep a small local supply for emergencies if your budget allows. The goal is fewer pharmacy surprises, not a new kind of last-pill panic.
Questions to Ask Before You Move a Maintenance Med
Before transferring a regular prescription, ask the cost-plus pharmacy:
- Is this exact drug, strength, and form available right now?
- Is the quote for 30 days or 90 days, and does it include shipping?
- How long does delivery usually take, and is there tracking?
- How is the medication packaged in hot or cold weather?
- Can I reach a pharmacist by phone or chat?
- What is the refund or replacement policy for damaged or lost orders?
- Will I get a receipt that works for my HSA or FSA?
- Does this purchase count toward my insurance deductible or out-of-pocket maximum?
The Bottom Line
A cost-plus pharmacy is not a replacement for your local pharmacist, your insurance plan, or your discount card. It is another price on the table. In 2026, with drug costs still pinch-hitting household budgets, that extra quote is worth having — especially for a stable generic you take every month.
Test it on one prescription first. Compare the total 90-day cost, not just the headline price. Keep urgent medications local. And if the savings are real, recheck the math when your plan year resets or your dose changes. Transparency is useful, but only when you run the numbers yourself.